

Instacart Shopper Rewards
4.3

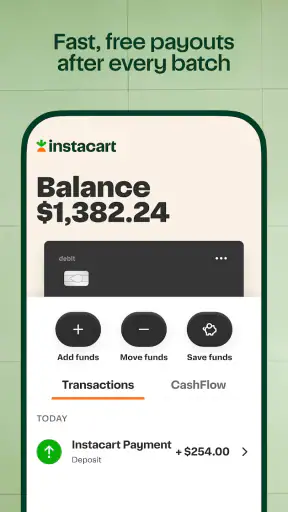
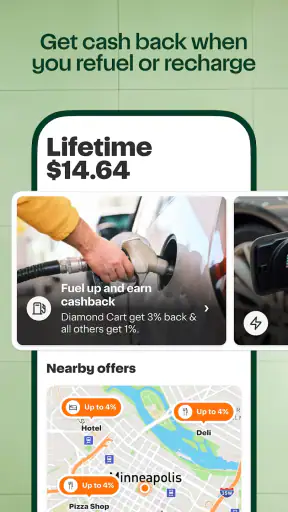
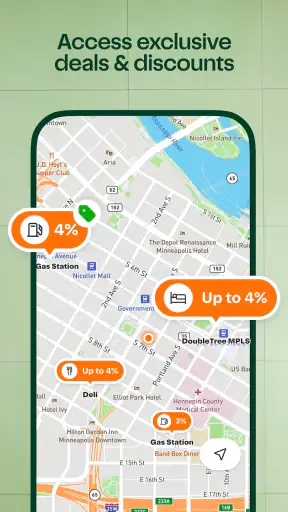
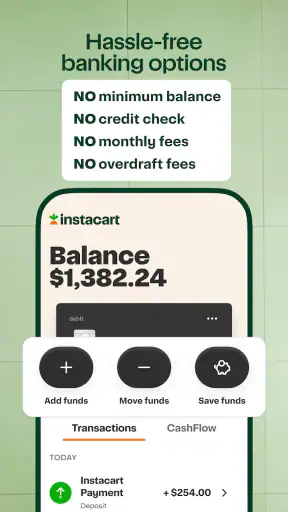
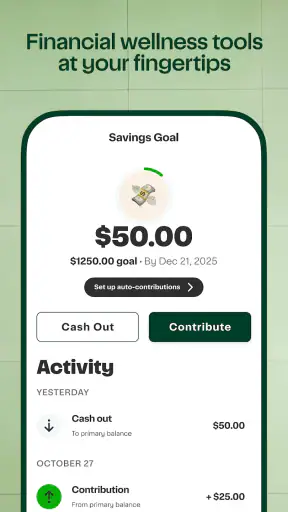
Instacart Shopper Rewards is a finance app aimed at people who earn through Instacart shopping and want a debit-card experience connected to that work. I found the idea easy to understand: instead of treating delivery income and everyday spending as completely separate routines, the app puts the shopper’s money tools in a mobile setting that can be used while moving between stores, checkout lines, and customer drop-offs.
That mobile focus matters more here than it would in a typical budgeting app. A shopper may open the app with one hand, in a parking lot, or between orders, so the quality of the experience depends not only on the screens themselves but also on the phone’s connection at that exact moment. My overall impression is that this is most useful for an Instacart shopper who wants a straightforward way to keep an eye on the debit-card side of work-related finances. It is less compelling for someone looking for a complete banking replacement or a detailed personal-finance dashboard.
How the app fits into a shopper’s working day
The app is developed by Branch Messenger and is listed as a free finance app for everyone. Its store positioning is centered on discovering a new debit card, while the short description identifies it as Instacart Shopper. That combination tells me the product is not trying to be a general-purpose money manager first. Its practical audience is narrower: people who need a financial tool that makes sense alongside Instacart shopping.
I would think of it as a companion for a particular work pattern rather than as a replacement for every financial app on a phone. A shopper might use it before starting a shift to check the account connected with card activity, then return to it after shopping to review what is available for fuel, food, or other daily expenses. The value comes from reducing the number of separate places where work-related money has to be mentally tracked.
That focus is also the first important trade-off. A specialized app can feel more relevant than a generic bank application, but it may not satisfy a user who wants extensive savings tools, investment features, household budgeting, or broad account aggregation. If your main goal is to manage a conventional checking account and several unrelated financial products, your existing bank may remain the better center of gravity.
The app has an average rating of 4.3 from around 500 ratings, with a little over 100 written reviews, and it has passed the 100K-plus install mark. Those figures suggest that it has found a real audience without making it look like a universal finance platform. I would treat the feedback as encouraging rather than conclusive: the app appears established enough to attract attention, but every shopper should still judge whether its workflow matches the way they actually earn and spend.
What happens when the connection is good
When mobile connectivity is stable, the app’s biggest advantage is convenience during short gaps in a busy route. I can imagine opening it after finishing an order, checking the relevant balance, and deciding whether to stop for fuel before accepting another batch. That is a small interaction, but it is exactly the kind of decision that makes a mobile finance tool worthwhile.
The best habit is to check important information before reaching a checkout or fuel pump, rather than waiting until payment is already the next step. A strong connection can still become unreliable inside a store, in a crowded parking area, or when the phone moves between networks. Using the app a little earlier gives the information time to load and leaves room to change plans if the screen does not respond.
For me, the key benefit is not simply speed. It is context. A normal bank app may show a balance, but this product is aimed at the circumstances of an Instacart shopper. That makes it easier to frame the money around a working day: what is available before the next route, what needs to remain reserved for transportation, and whether a purchase should wait until the shopper is back on a dependable connection.
There is also a useful distinction between checking information and acting on it. A balance screen may load quickly enough for a glance, while a card-related action or account update may need a more dependable connection and a few extra moments. I would avoid beginning any important transaction while walking into a store or driving away from a delivery. The app is designed for mobile use, but mobile use still benefits from deliberate timing.
Using it in real mobile situations
A realistic example is a shopper working an evening route. Before leaving home, I would open the app on a reliable network and check the money available for the day’s practical costs. After several orders, I might use a quiet minute in the car, while parked legally, to review the account before deciding whether to buy fuel or continue. If the app loads normally, that creates a simple rhythm: work, pause, check, and make the next decision.
The important detail is to separate financial checking from driving. The app belongs in the moments between trips, not while a vehicle is moving. That sounds obvious, but a finance tool built for mobile workers can tempt people to squeeze in a quick glance at the wrong time. I would make the habit automatic: stop, secure the car, then open the app.
Another useful workflow is to use a stronger connection for preparation and a mobile connection for brief checks. Before starting work, I would review anything important that requires more attention. During the route, I would keep interactions short and avoid repeatedly refreshing a screen simply because the signal is inconsistent. This reduces frustration and helps distinguish a genuine account issue from a temporary loading problem.
The app’s audience should also consider phone ergonomics. A shopper may be wearing gloves, carrying groceries, or working in bright sunlight. I found that the most practical use is a quick confirmation rather than extended financial planning. If you need to compare many categories of spending or build a detailed monthly budget, a larger screen and a more comprehensive finance service will probably be more comfortable.
When the network gets in the way
Connectivity is where the experience becomes less predictable. A finance app cannot be judged only by how it looks on a strong home connection; shoppers use it in supermarkets, apartment complexes, underground parking areas, and roads where coverage changes. A loading delay at home is a minor annoyance. The same delay when you are trying to confirm whether you can pay for an immediate necessity feels much more serious.
My advice is to avoid treating a blank or slowly loading screen as proof that the account is empty or that a payment has failed. First check the connection, wait without repeatedly tapping, and try again from a safer, stationary location. If the situation is urgent, use the normal support or account channels available to you rather than making several duplicate attempts that could create more confusion.
Recovery is easier when you build a small buffer into your routine. Before accepting a long sequence of orders, I would make sure I had already checked the information most likely to matter. I would also keep another payment method available for ordinary emergencies. That is not a criticism unique to this app; it is sensible whenever a phone, network, or financial service is part of a time-sensitive purchase.
There is a subtle difference between an app recovering gracefully and a user recovering gracefully. Even if the application eventually reconnects, the shopper may already have moved to the next task. I prefer to pause after a failed attempt, confirm whether anything actually went through, and only then repeat the action. This is especially important around card-related activity, where impatience can make it difficult to tell whether the problem was the network, the terminal, or the app session.
I would also avoid judging the whole product from one weak-signal moment. Network conditions can make a responsive app appear broken, while a stable connection can hide workflow annoyances. The fair test is to use it in the places where you genuinely work and to see whether its normal tasks remain manageable. For a shopper with dependable coverage, this may be a minor concern. For someone who regularly works in dead zones, it becomes central to the decision.
Keeping mobile data use sensible
For a finance app, data-conscious use is less about large downloads and more about avoiding unnecessary sessions. I would open it for a clear purpose, complete the check, and close it rather than leaving it running while moving between orders. Repeatedly refreshing balances during a weak connection is unlikely to improve the result and can consume attention as well as mobile data.
Wi-Fi is useful for setup, careful account review, and any task that feels too important to rush. Mobile data is better reserved for short, practical checks while working. This division also improves security habits: I prefer to handle sensitive financial activity on a connection I trust, then use the phone for limited confirmation when I am outside.
Notifications and background behavior are another reason to review the phone’s own settings. I would check which alerts are genuinely useful and avoid allowing every possible message to interrupt a shopping route. A finance app should help me make decisions, not turn every pause into another reason to look at the screen. If a shopper shares a device with family members or uses a phone with limited storage, keeping the app and its alerts tidy is even more worthwhile.
One non-obvious advantage of a focused workflow is that it can reduce the temptation to browse. A general banking app often contains many sections, offers, and unrelated products. Here, the shopper-oriented purpose gives me a reason to open the app and a reason to leave it. That can be helpful for people who want a quick work-money check rather than another place to spend time comparing financial products.
At the same time, a focused app should not become the only record of personal finances. I would still keep a separate habit of reviewing spending, setting aside money for recurring costs, and checking statements through the appropriate account tools. The app can support a shopper’s daily decisions, but it should not replace basic financial organization. That distinction is important for anyone whose income changes from week to week.
How it compares with ordinary alternatives
Compared with a standard bank app, Instacart Shopper Rewards feels more job-specific. A bank application is usually better when I need a broad view of checking, savings, transfers, bills, and other household money. This app makes more sense when the question is tied to Instacart shopping and the debit-card experience described in its listing.
Compared with a budgeting app, its strength is immediacy rather than analysis. Budgeting software may help divide income into categories, identify patterns, or plan a month in detail. A shopper-oriented debit app is more useful for the immediate question of what money is available while working. If I want to understand why my fuel spending rose over several months, I would choose a dedicated budgeting tool. If I want a practical check during a route, this app is the more natural fit.
Compared with using cash or a separate everyday card, the app offers a more direct connection to the shopper’s financial workflow. That can simplify mental accounting, but it also creates dependence on the phone and the network at moments when a physical alternative may feel more dependable. I would not encourage anyone to discard every backup payment option simply because a mobile debit experience is convenient.
The free price lowers the barrier to trying it, and the everyone age rating makes it broadly approachable. Still, “free” does not automatically mean it is the right financial home. The real question is whether the shopper-oriented design saves enough effort to justify adding another finance app to the phone. For an active Instacart shopper, the answer may be yes. For someone who rarely shops or does not need a separate work-money routine, the usual bank app may be simpler.
Who should use it, and who should skip it
I would recommend giving it a serious look if you regularly shop for Instacart, prefer handling work-related money from your phone, and value quick access over a large set of financial planning tools. It is particularly suitable for someone who can build checks into natural pauses during a route and who usually has reliable mobile coverage.
I would be more cautious if your work takes you through areas with poor reception and you often need immediate payment certainty. In that case, the app may still be useful, but only as part of a wider routine that includes preparation and a backup payment method. I would also skip it as a primary finance app if your needs center on investments, detailed budgeting, multiple banks, or complex household money management.
New users should begin with low-pressure tasks. Open the app at home, learn where the important account information appears, and test your normal sign-in and checking routine before relying on it during a busy shift. Then try it during a parked break in a familiar area. This approach reveals whether the app feels clear on your phone and whether your usual work locations provide a dependable enough connection.
The current version is 2026.8.2, and the app was released on August 6, 2025. I would keep it updated through the normal app-store process, especially for a finance product, but I would still avoid installing an update immediately before an important work period. A calm update at home is preferable to discovering a changed screen or a required restart while you are between orders.
My connectivity verdict
After looking at the app through the reality of mobile work, I see Instacart Shopper Rewards as a focused finance companion rather than a complete banking universe. Its strongest quality is relevance: it is built around the shopper’s relationship with a debit-card experience, so its purpose is easier to understand than that of a generic money app.
Its main weakness is not necessarily a missing feature; it is the environment in which it must be used. A shopper may need financial information precisely when reception is inconsistent, attention is divided, and time is limited. The safest and smoothest experience comes from checking important details before the route, using the app only while parked, and treating a failed load as a connection problem to investigate rather than an account result to guess at.
The app is free, carries an everyone rating, and has attracted a modest but meaningful user base with a 4.3 average. Those points make it reasonable to try if you are the intended Instacart shopper audience. My recommendation is conditional but positive: use it when its specialized workflow matches your work, keep your expectations narrower than you would for a full bank, and maintain a backup for moments when the phone or network cannot keep up.
The best reason to choose it is practical control during a shopping day, not a promise of replacing every other financial tool. If that is the problem you want to solve, the app deserves a place on your shortlist. If you need deep financial planning or dependable access in areas where your connection regularly disappears, a conventional bank app or a separate budgeting solution may serve you better.
4.3
141.00 Reviews
Pros
- Rewards can add extra value to frequent Instacart shopping activity.
- Progress and available benefits are easy to review in the shopper app.
- Useful for shoppers who already spend regularly on eligible purchases.
- Offers may help reduce costs on everyday essentials and services.
- Participation can complement regular earnings without changing delivery routines.
Cons
- Eligibility and rewards may vary by market
- account
- and shopper status.
- Some benefits can require meeting specific activity or spending conditions.
- Reward values and offers may change or expire with limited notice.
- Not every purchase or delivery activity may qualify for rewards.
- Tracking multiple terms and redemption rules can take extra attention.


